Disaster Survival Stocks: Companies That Could Benefit When Americans Prepare for the Worst

by Fred Fuld III

The recent wave of technology outages, airline groundings, and disruptions to critical services has given Americans something new to think about: How prepared are we if the systems we depend on every day suddenly stop working?

On November 13, 2026, the Federal Aviation Administration (FAA) experienced a telecommunications network failure that resulted in a nationwide ground stop. The disruption lasted approximately four hours and 45 minutes, with more than 12,000 flight cancellations reported that day. The problem affected 17 of the FAA’s 22 Air Route Traffic Control Centers. Although the FAA said that all aircraft landed safely, the incident demonstrated how a technical failure in one critical system can disrupt transportation across the country. 

There have also been other unsettling developments. United Airlines experienced a separate technology outage that disrupted flights at several major airports, including San Francisco International Airport. Meanwhile, the National Security Agency (NSA) experienced an outage of its internal classified information network on November 17. The NSA attributed the disruption to scheduled maintenance, and officials said there was no evidence of a cyberattack. Nevertheless, the incident raised questions about the reliability of even highly sophisticated government computer systems. 

These events have fueled concerns about how vulnerable modern society has become to technology failures, cyberattacks, power outages, natural disasters, and interruptions in essential services. People increasingly recognize that electricity, communications, transportation, banking, and food distribution systems are interconnected. A problem in one area can quickly affect many others.

For investors, this raises an interesting question: Are there publicly traded companies that could benefit financially if more Americans begin preparing for emergencies?

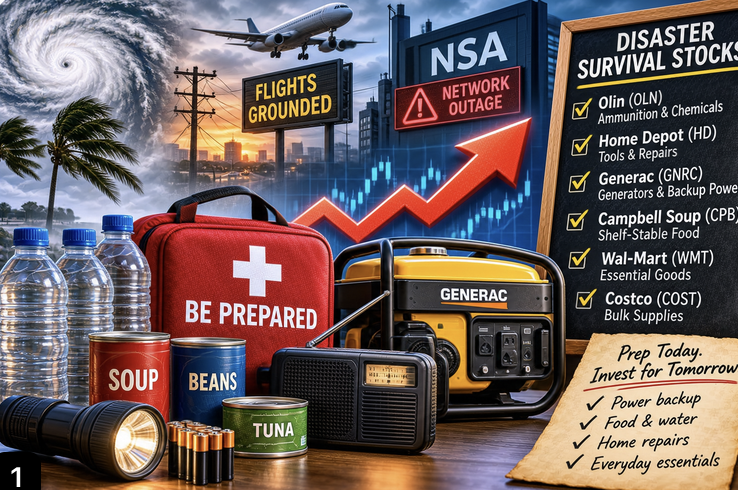
There is an investment theme that could be called disaster survival stocks. These are companies that manufacture or sell products people may want to have available when normal services are interrupted. They include generators, emergency supplies, canned food, bottled water, home improvement products, ammunition, and other necessities.

The recent events have also brought renewed attention to a group of people known as preppers.

The Prepper Movement Goes Mainstream

Preppers are people who take steps to prepare for emergencies, ranging from relatively ordinary situations such as hurricanes, earthquakes, and extended power outages to more extreme possibilities such as widespread infrastructure failures, economic disruptions, and societal breakdowns.

Traditional preppers often maintain supplies of food and water, backup electricity, first-aid equipment, emergency communications devices, and other necessities. Some have installed solar panels, battery storage systems, and generators. Others maintain gardens, preserve their own food, store fuel, and develop plans for living without conventional utilities.

What is particularly interesting is that emergency preparedness is no longer limited to people who consider themselves survivalists.

A November 19, 2026, Washington Post report described Americans buying emergency supplies following the recent outages. Purchases included bottled water, canned food, battery-powered radios, portable generators, solar power stations, and propane supplies. One consumer reportedly spent approximately $3,500 expanding his emergency inventory. The article also reported unusually strong interest in generators at Costco, with 21 of the 26 most expensive generators listed on its website sold out as of the preceding Sunday. 

An additional report from Axios described a substantial increase in emergency-preparedness shopping, with one survival-gear retailer reporting a 450% increase in sales between October 27 and November 16 compared with preceding weeks. 

Whether these developments represent a temporary reaction to the headlines or the beginning of a longer-term trend remains to be seen. However, they could create opportunities for companies that supply the products associated with emergency preparedness.

Here are six publicly traded companies that investors and traders may want to investigate.

1. Olin Corporation (NYSE: OLN)

A Chemicals and Ammunition Play

Emergency supplies exposure

NYSE: OLN

Olin is an interesting, somewhat unconventional disaster-preparedness investment because it operates two businesses that could be relevant during periods of heightened emergency preparedness. Its Winchester division manufactures ammunition, including products for recreational shooting, hunting, law enforcement, and military applications. Its other operations produce chemicals, including chlorine, caustic soda, and epoxy products.

Ammunition is an established component of the prepper market, particularly among individuals interested in hunting, personal protection, and self-sufficiency. Increased consumer interest in emergency preparedness could potentially support ammunition demand, although Winchester’s business is much broader than the prepper market.

Olin reported third-quarter 2026 sales of approximately $1.75 billion and net income of $14.4 million, compared with $42.8 million in the prior-year quarter. Adjusted EBITDA was $191.4 million, down from $222.4 million. The company is also pursuing a merger with Huntsman, which it expects to close in the first quarter of 2027, subject to regulatory approvals. 

Investment consideration: Winchester provides an interesting angle on the preparedness theme, but investors should remember that Olin is primarily a cyclical chemical company. Its earnings are sensitive to industrial demand, energy costs, chemical prices, and operating conditions. Its substantial debt and proposed merger also deserve attention.

2. The Home Depot (NYSE: HD)

The Emergency Repair and Equipment Play

NYSE: HD

Home Depot is one of the more obvious companies that could benefit when homeowners decide they need to become more self-sufficient. The company sells generators, power tools, flashlights, batteries, building materials, plumbing supplies, electrical equipment, and other products that become particularly important when homes experience damage or utility interruptions.

After a hurricane, wildfire, earthquake, or extended power outage, homeowners frequently need equipment and materials to restore their properties. Portable generators, extension cords, chainsaws, tarps, water pumps, and electrical supplies can all experience increased demand.

Home Depot also benefits from longer-term trends that have little to do with disasters, including aging housing stock, remodeling, maintenance, and professional contractor spending.

The company reported fiscal third-quarter 2026 sales of $43.4 billion, up 4.9% from the prior-year quarter. Comparable-store sales increased 2.2%, while earnings were $3.72 per diluted share. Management projected approximately 4.5% full-year sales growth for fiscal 2026. 

Investment consideration: Home Depot offers exposure to disaster-related repairs and preparedness without relying exclusively on emergency purchases. However, higher interest rates, weak housing turnover, and reduced consumer spending on remodeling could affect growth.

3. Generac Holdings (NYSE: GNRC)

The Backup Electricity Play

One of the most direct beneficiaries

NYSE: GNRC

Generac may be one of the most direct ways to invest in the disaster-preparedness trend. The company manufactures standby generators, portable generators, battery storage systems, and other energy technology products.

For homeowners, a standby generator can automatically provide electricity when the utility grid goes down. This can be particularly important for people who depend on electricity for medical equipment, refrigeration, heating, air conditioning, security systems, and communications.

The company also sells commercial and industrial backup power systems. Hospitals, data centers, telecommunications facilities, businesses, and other critical operations require dependable backup electricity.

An especially interesting development is the growing demand for backup power from data centers. Generac announced a long-term supply agreement with Amazon that includes an expected $2.4 billion in initial generator deliveries during 2027 and 2028.

Generac’s third-quarter 2026 results were impressive. Net sales increased 16% to a record $1.29 billion, while net income rose to $109 million from $66 million in the prior-year quarter. Residential sales increased approximately 9%, supported by stronger demand for home standby and portable generators. The company maintained its full-year sales growth guidance in the mid-to-high teens percentage range. Its data-center product backlog reached approximately $4.5 billion. 

Investment consideration: Generac is particularly attractive as a way to participate in the longer-term need for backup electricity, including data-center demand. However, the stock can be sensitive to weather patterns, residential construction, interest rates, and the timing of generator purchases. Competition and execution risks associated with its expanding industrial business should also be considered.

4. The Campbell’s Company (NASDAQ: CPB)

The Shelf-Stable Food Play

NASDAQ: CPB

Food is one of the most basic components of emergency preparedness. When people worry about disruptions to grocery stores, transportation, or electricity, they often begin stocking their pantries with products that have long shelf lives.

Campbell’s is well positioned in this category through its soup, canned food, sauces, snacks, and other packaged food products. Its well-known brands include Campbell’s, Prego, Pace, Swanson, and Goldfish.

Canned soup and other shelf-stable foods are particularly useful during emergencies because they can be stored for extended periods and many varieties can be consumed with little preparation.

Unlike companies that sell generators or emergency equipment, Campbell’s has a business that is not dependent on consumers making large discretionary purchases. Food is something people need regardless of economic conditions.

However, investors should be aware that Campbell’s has recently encountered financial difficulties. For fiscal 2026, annual sales declined 5% to $9.7 billion, while adjusted earnings per share declined 27% to $2.17. The company announced a dividend reset as part of a strategy to accelerate debt reduction. It is also targeting $500 million in cost savings by fiscal 2030. 

Investment consideration: Campbell’s offers defensive consumer staples exposure, but investors should not assume that increased emergency food purchases will automatically translate into substantial earnings growth. Competition, consumer preferences, food input costs, and the company’s debt reduction efforts are important considerations.

5. Walmart (NASDAQ: WMT)

The Essential Goods Distribution Play

NASDAQ: WMT

Walmart could be one of the biggest beneficiaries of increased consumer interest in emergency preparedness simply because of its enormous retail distribution network.

The company sells virtually everything consumers might need during an emergency, including bottled water, canned food, batteries, flashlights, first-aid supplies, over-the-counter medications, blankets, coolers, portable power equipment, and household necessities.

Its combination of physical stores, distribution centers, and e-commerce operations gives it an advantage in making essential products available to consumers. Walmart’s grocery business is particularly important because food represents a large portion of household emergency supplies.

There is also an important distinction between Walmart and some of the other companies discussed here. Walmart does not need a major disaster to generate sales. It sells everyday necessities that consumers purchase regularly, regardless of whether they are preparing for an emergency.

Walmart reported third-quarter fiscal 2027 revenue of $188.8 billion on November 19, 2026, an increase of 5.2%. E-commerce sales increased 17% globally, and the company raised its full-year outlook. Operating income increased 16%. 

Investment consideration: Walmart offers a relatively diversified way to participate in the emergency-preparedness theme. Its scale, pricing power, and everyday grocery business provide some defensive characteristics. However, its valuation, labor costs, competitive pressures, and retail profit margins should be examined before purchasing shares.

6. Costco Wholesale (NASDAQ: COST)

The Bulk Purchasing and Stockpiling Play

Recent demand evidence

NASDAQ: COST

Costco might be one of the most interesting companies in this group because its warehouse business is naturally suited to consumers who want to purchase large quantities of essential goods.

Its merchandise includes bulk bottled water, canned food, paper products, batteries, first-aid supplies, household necessities, and emergency equipment. Costco also sells generators and other power-related products.

The membership warehouse model encourages consumers to buy larger quantities than they might purchase at a conventional grocery store. This is particularly attractive to households that want to maintain an emergency supply of food and other essentials.

There is already evidence that recent events have generated increased interest in Costco’s emergency-preparedness merchandise.

According to a November 2026 report citing Mizuho Securities, 21 of the 26 most expensive generators listed on Costco’s website were sold out as of November 15. Analysts also attributed some of the company’s stronger October comparable-store sales to emergency-preparedness purchases. 

Costco reported fiscal 2026 annual sales of approximately $297.2 billion, up 10.1% from the previous year. Fourth-quarter net income increased to approximately $3.0 billion from $2.61 billion. Its October 2026 sales increased 12.6% to $24.5 billion. 

Investment consideration: Costco has an attractive business model, recurring membership income, and a loyal customer base. It could benefit from increased stockpiling, but emergency purchases are only a small part of its overall business. Its valuation is also an important consideration. Investors should avoid assuming that a temporary surge in preparedness shopping justifies paying an excessive earnings multiple.

Other stocks worth investigating

The six companies above are not the only publicly traded businesses that could benefit from increased emergency preparedness.

CompanySymbolPotential opportunity
Tractor SupplyTSCOGenerators, propane, livestock supplies, tools, and ammunition
Energizer HoldingsENRBatteries and portable lighting
KenvueKVUEFirst-aid and personal care products
Procter & GamblePGHygiene, cleaning, and household necessities
American Water WorksAWKEssential water infrastructure
First SolarFSLRSolar energy infrastructure
Lowe’sLOWGenerators, tools, building materials, and repair supplies

These companies provide additional exposure to different aspects of emergency preparedness, from portable power and food production to water infrastructure and home repairs.

What Are the Biggest Investment Risks?

Although disaster preparedness is an interesting investment theme, investors should distinguish between a temporary increase in consumer purchases and a sustained change in spending behavior.

A major outage or natural disaster can produce a sudden increase in demand for generators, bottled water, canned food, batteries, and other supplies. However, consumers may already have purchased these products, reducing the need for repeat purchases.

For example, a household that buys a generator may not need another one for 10 or 15 years. Similarly, people who stock their pantries with canned goods may not need to replenish their supplies immediately.

There is also the risk that investors will overreact to headlines. A stock can rise substantially on expectations of higher demand even if the actual increase in company earnings is relatively small.

Valuation is especially important. Costco, for example, has a strong business, but its shares have historically commanded a premium valuation. Campbell’s has a more defensive food business, but its recent financial results illustrate that even companies selling essential products can experience declining earnings.

Finally, these companies are exposed to different economic forces. Olin is affected by industrial chemical demand, Generac by generator purchasing cycles and data-center investment, and Home Depot by the housing and remodeling markets.

Conclusion: Building a Disaster-Preparedness Investment Watchlist

The recent technology outages, airline disruptions, and NSA network incident have highlighted an important vulnerability of modern society: We depend on interconnected systems that can sometimes fail unexpectedly.

Whether these incidents prove to be isolated technical problems or part of a broader trend, they have reminded consumers of the importance of having backup plans.

From an investment perspective, I would put Generac near the top of the list because it provides direct exposure to backup electricity, a market that has opportunities beyond residential emergency preparedness, particularly with data centers. Home Depot is another interesting candidate because it sells the equipment and materials needed to prepare for and recover from disasters.

Walmart and Costco provide exposure to consumers stocking up on necessities, while Campbell’s offers exposure to shelf-stable food. Olin is a more specialized investment, with its Winchester ammunition business providing an additional angle on the preparedness market.

I would be particularly interested in monitoring whether the recent increase in emergency-preparedness shopping translates into sustained sales growth over the next several quarters. If consumers begin making preparedness a regular part of household budgeting rather than simply reacting to alarming headlines, some of these companies could benefit from a meaningful long-term business trend.

The key for investors and traders is not to bet on a disaster occurring. It is to identify companies that sell products people increasingly value because they want to be prepared if one does.

This article is for informational and investment research purposes only. It is not a recommendation to buy or sell any particular security. Investors should examine current valuations, earnings, balance sheets, and risk factors before making investment decisions. No investment recommendations are expressed or implied.
The Chip Design Software Duopoly: Cadence and Synopsys Stand to Benefit From the AI Revolution

by Fred Fuld III

The artificial intelligence revolution has created tremendous opportunities for semiconductor manufacturers, including companies that make the processors powering data centers, artificial intelligence systems, autonomous vehicles, smartphones, and other advanced electronics. However, an important group of companies operates behind the scenes, providing the software engineers use to design those increasingly sophisticated chips.

Two of the biggest beneficiaries of this trend are Cadence Design Systems (NASDAQ: CDNS) and Synopsys (NASDAQ: SNPS). Both companies specialize in electronic design automation (EDA), a category of software that allows semiconductor engineers to design, simulate, test, and verify integrated circuits before they are manufactured.

With market capitalizations of approximately $90 billion for Cadence and $88 billion for Synopsys, these companies are among the largest publicly traded businesses focused on chip design technology. Their importance is growing as semiconductor designs become more complicated and the demand for computing power continues to accelerate.

Unlike semiconductor manufacturers such as Nvidia, AMD, and Intel, Cadence and Synopsys do not depend on selling physical chips. Instead, they sell the essential software and intellectual property that make it possible for semiconductor companies to develop their products. This business model can produce recurring revenue, high profit margins, and substantial cash flow.

Why Chip Design Software Is Becoming More Important

Designing a modern semiconductor is an extraordinarily complicated undertaking. Today’s advanced processors can contain tens of billions of transistors, with individual components measuring only a few nanometers.

Engineers must determine how those transistors will be arranged, how electrical signals will travel between them, how much heat they will generate, and whether the finished design will function reliably.

EDA software handles many of these tasks. It allows engineers to create circuit layouts, simulate performance, identify design errors, verify functionality, and prepare designs for manufacturing.

The software is particularly important in the development of artificial intelligence processors. AI chips require enormous computing capacity, high-speed memory connections, sophisticated packaging, and efficient power management. These requirements increase the complexity of chip development and create additional demand for advanced design software.

There is also a significant competitive advantage for established EDA companies. Semiconductor manufacturers invest considerable time and money training engineers to use particular software platforms. Switching to another provider can be expensive and disruptive. This creates customer relationships that can last for many years.

Although several companies participate in the broader electronic design and engineering software industry, Cadence and Synopsys are the two dominant publicly traded specialists in this market.

Cadence Design Systems (NASDAQ: CDNS)

Founded in 1988 through the merger of SDA Systems and ECAD, Cadence Design Systems has grown into one of the world’s leading suppliers of electronic design automation software.

The company provides a broad collection of tools used throughout the semiconductor development process. Its software helps engineers design integrated circuits, verify their operation, simulate electrical characteristics, and optimize performance before sending designs to semiconductor foundries for manufacturing.

Cadence also offers software for printed circuit boards, advanced semiconductor packaging, computational fluid dynamics, and other system-level engineering applications. In addition, it licenses semiconductor intellectual property, allowing customers to incorporate proven design components into their own chips.

This diversification gives Cadence exposure to more than just traditional chip design. Its products are used in developing AI processors, networking equipment, automotive electronics, aerospace systems, and other sophisticated technologies.

Financial performance

Cadence reported third-quarter 2026 revenue of approximately $1.63 billion, an increase of 22% from $1.34 billion in the comparable quarter of 2025. Revenue for the first nine months of 2026 reached $4.69 billion, compared with $3.86 billion during the same period a year earlier.

The company’s third-quarter non-GAAP operating margin was 44.1%, demonstrating the profitability of its software-oriented business model. Non-GAAP diluted earnings per share were $2.11, compared with $1.93 in the year-earlier quarter.

Cadence ended the third quarter with a record backlog of $8.2 billion, an important indication of future business commitments.

Management raised its 2026 revenue forecast to approximately $6.39 billion to $6.42 billion, representing expected annual growth of approximately 21%. Its full-year non-GAAP earnings-per-share forecast was $8.37 to $8.43.

These results illustrate the company’s ability to increase revenue while maintaining substantial operating profitability. Cadence Investor Relations+1

Growth opportunities

One of Cadence’s most promising opportunities is the increasing use of artificial intelligence in semiconductor design itself. The company is developing AI-powered tools that can help engineers automate portions of the design process, improve productivity, and identify potential problems more quickly.

In October 2026, Cadence announced its Maestro portfolio of specialized AI models for chip and system design. The company also reported more than 100 active customer engagements involving its AI Super Agents.

Another important opportunity is advanced semiconductor packaging. As traditional methods of increasing chip performance become more challenging, manufacturers are increasingly combining multiple chip components into sophisticated packages. This creates additional engineering requirements and demand for Cadence’s software.

The company is also benefiting from demand for high-performance computing, data center infrastructure, memory technology, and networking equipment.

Cadence’s substantial backlog and recurring software revenue provide a degree of visibility into future business activity.

Synopsys (NASDAQ: SNPS)

Synopsys was founded in 1986 and has become one of the most important suppliers of semiconductor design software in the world. Like Cadence, its products are used by semiconductor companies to design, simulate, verify, and optimize integrated circuits.

Synopsys offers a comprehensive collection of electronic design automation tools, including software for digital chip design, verification, testing, and manufacturing preparation. Its products are used by major semiconductor manufacturers, including companies developing processors for artificial intelligence, mobile devices, automobiles, and data centers.

One of the company’s important competitive advantages is its extensive portfolio of semiconductor intellectual property. Rather than designing every component of a chip from scratch, semiconductor companies can license proven building blocks from Synopsys and incorporate them into their own designs.

These products include processor-related IP, memory components, high-speed interfaces, and other technologies. This business creates another source of revenue beyond traditional software licensing.

The Ansys acquisition

An important development in Synopsys’ history was its acquisition of Ansys in 2025. Ansys is a leading provider of engineering simulation software used in industries including aerospace, automotive, electronics, and industrial manufacturing.

The acquisition significantly expanded Synopsys’ capabilities beyond traditional semiconductor design. Engineers can now use a more integrated collection of software to design a chip and simulate how the larger electronic system will perform under real-world conditions.

For example, designing an AI processor involves more than determining how transistors will operate. Engineers must also consider heat generation, electrical characteristics, packaging, and cooling requirements. Ansys’ simulation technology complements Synopsys’ existing design capabilities.

The acquisition also gives Synopsys opportunities to sell additional products to existing customers and expand into adjacent engineering markets.

Financial performance

Synopsys reported third-quarter fiscal 2026 revenue of approximately $2.48 billion, compared with $1.74 billion in the same quarter of fiscal 2025, an increase of approximately 42%.

The company reported GAAP net income of $545.8 million, or $2.84 per diluted share, compared with $242.5 million, or $1.50 per share, in the prior-year quarter. Non-GAAP earnings were $3.91 per share, compared with $3.39 a year earlier.

For the first nine months of fiscal 2026, revenue totaled approximately $7.16 billion, compared with $4.80 billion in the comparable period of 2025.

Management raised its full-year fiscal 2026 revenue forecast to approximately $9.69 billion to $9.74 billion. The forecast includes approximately $2.98 billion of expected Ansys revenue.

Synopsys also projected approximately $2.8 billion in operating cash flow and $2.6 billion in free cash flow for fiscal 2026. Its full-year non-GAAP earnings-per-share forecast was approximately $15.04 to $15.10.

An important distinction when evaluating these figures is that the acquisition of Ansys substantially increased the company’s reported revenue. Consequently, some of the growth reflects the addition of an acquired business rather than organic expansion. Synopsys Investor Relations

Growth opportunities

Synopsys has several attractive long-term growth opportunities.

The first is the continued expansion of artificial intelligence. AI processors are becoming more sophisticated, requiring advanced semiconductor designs, high-speed connections, and increasingly complicated verification processes. This should create demand for Synopsys’ software and semiconductor IP.

The second opportunity is the integration of its traditional chip design products with Ansys’ engineering simulation technology. The ability to simulate the performance of an entire electronic system, rather than just an individual chip, could make Synopsys’ product portfolio more valuable to customers.

A third opportunity involves advanced packaging and chiplets. Rather than placing all computing functions on one large piece of silicon, manufacturers are increasingly combining multiple smaller chips into a single package. This approach requires sophisticated design and verification software.

Synopsys is also investing in AI-assisted design automation, which could help engineers accomplish more work in less time. If these technologies become widely adopted, they could create additional licensing opportunities and strengthen customer relationships.

Comparing the two companies

Cadence and Synopsys are remarkably similar businesses, but there are some important differences.

CharacteristicCadenceSynopsys
Stock symbolCDNSSNPS
Approx. market cap (user-supplied)$90B$88B
Latest reported quarterly revenue$1.63B$2.48B
Quarterly revenue growth22%42%
Latest reported non-GAAP operating margin44.1%41.5% full-year guidance
FY2026 revenue outlook$6.39–$6.42B$9.69–$9.74B
FY2026 non-GAAP EPS outlook$8.37–$8.43$15.04–$15.10
Major differentiatorChip design and system analysisChip design, IP and Ansys simulation

Figures are in U.S. dollars. Synopsys’ margin figure is its full-year forecast, not its latest quarterly margin. Fiscal periods and non-GAAP measures differ. Market capitalizations are approximate inputs, not independently verified November 14 closing valuations.

Both companies have strong competitive positions, but their growth rates and business mixes are somewhat different. Synopsys is now the larger company by revenue, partly because of Ansys, while Cadence has demonstrated impressive organic growth in its latest reported quarter.

The broader industry is highly concentrated. Synopsys, Cadence, and Siemens EDA collectively account for the overwhelming majority of the global EDA market. This concentration reflects the difficulty of developing software capable of handling the enormous complexity of modern semiconductor designs.

Potential risks for investors

Despite their attractive business models and growth prospects, Cadence and Synopsys are not without risks. There are several issues investors should consider before purchasing either stock.

1. High stock valuations

Perhaps the biggest risk is valuation. Both companies have benefited from enthusiasm surrounding artificial intelligence and the semiconductor industry. Investors have been willing to pay substantial premiums for businesses that are expected to benefit from AI spending.

Even if both companies continue to report strong financial results, their stocks could decline if earnings growth fails to meet Wall Street expectations.

A slowdown in AI-related capital expenditures, a reduction in semiconductor industry growth, or a change in investor sentiment toward expensive technology stocks could pressure their share prices.

2. Dependence on semiconductor industry spending

Although Cadence and Synopsys have recurring revenue, they are not completely insulated from economic cycles.

If semiconductor manufacturers reduce their research and development budgets, delay new chip projects, or postpone investments in new manufacturing technologies, demand for design software could eventually be affected.

The rapid growth of AI spending has been a major industry tailwind. A slowdown in that spending would be an important risk.

3. Competition and technological disruption

Both companies compete with Siemens EDA, as well as smaller specialized software developers and emerging Chinese competitors.

China has been investing in developing its own semiconductor design software industry. If Chinese companies develop competitive alternatives, they could eventually reduce the market opportunities available to American EDA providers.

There is also the possibility that advances in artificial intelligence could change how semiconductor design software is developed and used. Although Cadence and Synopsys are investing heavily in AI themselves, they must continue innovating to maintain their competitive advantages.

4. Geopolitical and export restrictions

The semiconductor industry is particularly sensitive to U.S.-China trade relations. Government restrictions on the export of advanced semiconductor technology and related software could limit the ability of Cadence and Synopsys to sell certain products in China.

Synopsys has specifically identified export restrictions and geopolitical uncertainty as factors affecting its business in China. These restrictions could also affect customer demand and future design activity.

5. Acquisition and integration risks

Synopsys faces an additional risk associated with its acquisition of Ansys. Integrating two large technology companies can be complicated and expensive. Management must successfully combine operations, retain key employees, maintain customer relationships, and realize the expected financial benefits.

The acquisition also adds substantial amortization expenses and other adjustments that make comparisons between GAAP and non-GAAP earnings particularly important.

Investors should monitor debt levels, interest expense, free cash flow, and the progress of integration.

The long-term outlook: An attractive industry with significant barriers to entry

The long-term outlook for semiconductor design software appears promising. The increasing complexity of chips, growing use of AI, expansion of data centers, and development of autonomous vehicles and other advanced electronic systems should create opportunities for both Cadence and Synopsys.

One particularly interesting aspect of this industry is that these companies can benefit from the growth of multiple semiconductor manufacturers rather than having to predict which chip manufacturer will ultimately dominate the market.

For example, whether Nvidia, AMD, Broadcom, Intel, or another semiconductor company develops the next generation of successful processors, the engineers designing those products will need sophisticated software tools.

This makes Cadence and Synopsys somewhat different from individual semiconductor manufacturers. They are selling the tools that help the entire industry advance.

According to a 2026 PwC industry report, the global EDA market was estimated at approximately $15.2 billion in 2024 and is projected to reach $26.8 billion by 2030, representing an estimated annual growth rate of approximately 9.9%. This provides an indication of the potential expansion of the underlying market.

Which stock is more attractive?

Both companies have compelling competitive advantages, but investors may want to consider their different strengths.

Cadence (CDNS) offers a relatively straightforward way to participate in the growth of semiconductor design software. Its latest results show strong revenue growth, high operating margins, and a record backlog. Its expansion into AI-powered design tools and advanced system simulation provides additional growth opportunities.

Synopsys (SNPS) offers a broader technology platform following its Ansys acquisition. Its combination of semiconductor design software, intellectual property, and engineering simulation gives it opportunities to expand its relationships with customers and sell a wider range of products. However, investors need to monitor acquisition-related expenses, debt, and integration progress.

There is also an important valuation consideration. Based on the approximate market capitalizations supplied, Cadence trades at roughly 14 times its projected fiscal 2026 revenue, while Synopsys trades at approximately 9 times projected revenue. These are rough comparisons using the supplied market caps and company revenue forecasts, not enterprise-value multiples. Synopsys’ multiple is also affected by its newly acquired Ansys business.

Neither stock should automatically be considered inexpensive simply because its business prospects are attractive. Investors should examine forward P/E ratios, free cash flow, organic revenue growth, and the amount of acquisition-related adjustments included in reported earnings.

Conclusion

Cadence and Synopsys are two of the most interesting companies in the semiconductor technology industry. They occupy an important position in the AI ecosystem, providing the software and intellectual property necessary to design the advanced processors that power artificial intelligence, cloud computing, and other emerging technologies.

Their established customer relationships, high barriers to entry, recurring revenue, and substantial research and development investments provide competitive advantages that could persist for many years.

For investors looking beyond the semiconductor manufacturers themselves, these two companies offer an alternative way to participate in the growth of the AI and semiconductor industries.

The biggest question is not whether advanced chips will require increasingly sophisticated design software. They almost certainly will. The question for investors is whether the anticipated growth is already reflected in the stock prices.

As with any investment, prospective shareholders should compare current valuations with expected earnings and cash-flow growth rather than relying solely on the attractiveness of the underlying industry.

Financial data cutoff: November 14, 2026. The latest reported results used here are Cadence’s third quarter of calendar 2026 and Synopsys’ third quarter of fiscal 2026. Market capitalizations are approximate figures. No investment recommendations are expressed or implied.
Great Cash Bonus Offers

Chase Bank – Get Up to $650

Chase Bank is offering bonuses ranging from $175 to $650 if you open a checking account with them. There are three different options:

Chase Secure Banking℠
Simple banking essentials with no overdraft fees. Earn a $175 bonus with qualifying activities — no minimum deposit required. $0 or $4.95 Monthly Service Fee.

Chase Total Checking ®

Our most popular checking account. Earn a $400 bonus — requires $1,000 direct deposit within 90 days, $0 or $15 Monthly Service Fee.

Chase Premier Plus Checking℠
Premium checking with relationship benefits. Earn a $650 bonus — make deposits totaling $15,000 or more in new money within 30 days of offer enrollment and maintain $15,000 balance for 90 days from offer enrollment. Opens overlay $0 or $25 Monthly Service Fee.

This is a limited time offer that may only last until the end of the month.

American Express – Get Up to $200

American Express is offering up to $200 after you spend $2,000 in purchases on your new Blue Cash Everyday Card within the first 6 months of Card Membership. Welcome offers vary and you may not be eligible for an offer.

Apply, and if approved:
Find out your offer amount
Accept the Card with your offer
Spend $2,000 in 6 months
Receive the cash back

Cash back is received in the form of Reward Dollars that can be redeemed for a statement credit or at Amazon.com checkout.

Kalshi – $25 Sign Up Bonus

Make predictions on sports, politics, and more. Trade $25 to unlock, get a $25 bonus. New customers only.

Robinhood – Up to $200 in Stock

Open an account with Robinhood and get up to $200 worth of stock, which you can choose out of 26 companies. Don’t forget to add money to your account.

You’re guaranteed at least $5 once you link your bank, but 1 in 100 customers get $20, and 1 in 1,000 get $200.

TurboTax – Get 20% Off

Save 20% on TurboTax Online or TurboTax Experts federal products when you file with this link.

Many of these offers are available for a limited time, so act now if you are interested.

If you sign up or make a purchase through one of these links, we may receive compensation—at no extra cost to you

Stocks Going Ex Dividend in November 2026

The following is a short list of some of the many stocks going ex-dividend during the next month, which can be helpful for traders and investors interested in the stock trading technique known as “Buying Dividends” or “Dividend Capture.” This strategy involves purchasing stocks before the ex dividend date and selling them shortly after the ex-date at a similar price, while still being eligible to receive the dividend payment.

Although this dividend capture strategy generally proves effective in bull markets and flat or choppy markets, it is advisable to exercise caution and consider avoiding this strategy during bear markets. To qualify for the dividend, it is necessary to buy the stock before the ex-dividend date and refrain from selling it until on or after the ex-date.

However, it is important to note that the actual dividend may not be paid for several weeks, as the payment date may not be until two months after the ex-dividend date.

For investors seeking a comprehensive list of stocks going ex-dividend in the near future, WallStreetNewsNetwork.com has compiled a downloadable list containing numerous dividend-paying companies. Here are a few examples showcasing the stock symbol, ex-dividend date, periodic dividend amount, and annual yield.

CompanySymbolEx-dividend dateDividend/ shareCurrent yield
AppleAAPLNov. 10$0.270.31%
VisaVNov. 11$0.670.67%
Eli LillyLLYNov. 13$1.730.55%
Exxon MobilXOMNov. 17$1.032.30%
MicrosoftMSFTNov. 19$0.980.74%
Johnson & JohnsonJNJNov. 24$1.342.10%

To access the entire list of numerous ex-dividend stocks, subscribers will receive an email in the next couple days with the full list. If you are not already a subscriber, you can sign up using the provided signup box on this page. Don’t miss out on this valuable information, and the best part is that it’s free!

Dividend Definitions

To better understand the dividend-related terms, let’s define them:

Declaration date: This refers to the day when a company announces its intention to distribute a dividend in the future.
Ex-dividend date: On this day, if you purchase the stock, you would not be eligible to receive the upcoming dividend. It is also the first day on which a shareholder can sell their shares and still receive the dividend.
Record date: This marks the day when you must be recorded on the company’s books as a shareholder to qualify for the dividend. Typically, the ex-dividend date is set two business days prior to the record date.
Payment date: This is the day on which the dividend payment is actually made to the eligible shareholders. It’s important to note that the payment date can be as long as two months after the ex-date.

Before implementing the “Buying Dividends” technique, it is crucial to reconfirm the ex-dividend date with the respective company to ensure accuracy and avoid any unexpected changes.

In conclusion, being aware of the stocks going ex-dividend can be advantageous for traders and investors employing the “Buying Dividends” strategy. WallStreetNewsNetwork.com provides a convenient resource to access a comprehensive list of such stocks, allowing individuals to plan their investment decisions effectively. Remember to stay informed and consider market conditions before employing any investment strategy.

Disclosure: Author may have positions in some of the above at the time the article was written. No investment recommendations are expressed or implied.
If I Had Only Invested Then: Investor’s Time Machine

by Fred Fuld III

Have you ever had a Woulda, Shoulda, Coulda moment?

If you invested $10,000 in Google’s IPO at $85 per share in August 2004:

  • Initial investment: $10,000
  • IPO price: $85
  • Original shares: 117.65 shares
  • Google subsequently had a 2-for-1 split in 2014 and a 20-for-1 split in 2022.
  • Your original 117.65 shares would therefore have become approximately 4,706 shares.

Your $10,000 would be worth approximately:

$1,638,000

That’s roughly a 164-to-1 increase, or a gain of about $1.63 million, before considering dividends and taxes.

Another way to look at it: Google’s original $85 IPO price is equivalent to only about $2.13 per share today after the two stock splits.

So someone who put $10,000 into Google at the IPO and simply held it would have turned it into well over $1.6 million.

s is a fascinating comparison because all five became extraordinary investments, but Microsoft and Nvidia stand out.

I’ll use $10,000 invested at each company’s IPO, assume the shares were held continuously, account for all stock splits, and value them at the October 7, 2026 closing prices. I am not including dividends or taxes.

CompanyIPOIPO Price$10,000 IPO InvestmentValue Oct. 7, 2026Multiple
Microsoft (MSFT)1986$21$10,000$72.65 million7,265×
Nvidia (NVDA)1999$12$10,000$47.22 million4,722×
Apple (AAPL)1980$22$10,000$34.28 million3,428×
Amazon (AMZN)1997$18$10,000$34.66 million3,466×
Google (GOOGL)2004$85$10,000$1.65 million165×

The October 7 closing prices used were approximately GOOGL $350.50, AMZN $259.92, AAPL $336.67, MSFT $529.76 and NVDA $236.12. 

The really interesting part: Nvidia

Nvidia’s $12 IPO price has been reduced by its numerous stock splits to an equivalent of only $0.05 per current share.

So your $10,000 would have bought:

833.33 original Nvidia shares → 200,000 current shares

At $236.12, that’s approximately $47.2 million.

Microsoft is the winner

Microsoft’s IPO was $21. After its numerous stock splits, the original $21 IPO share represents 288 current shares.

Thus, your $10,000 would have purchased about 476.19 original shares, which became approximately 137,143 current shares.

At $529.76, that’s about:

$72.65 million.

And this calculation actually understates the total return, because Microsoft has paid substantial dividends over the years.

One important correction to my earlier Google calculation

I used Google’s Class A (GOOGL) price here. The original 2004 IPO included both Class A and Class B shares, and today’s share-class structure is more complicated. For a clean comparison, I’m treating the IPO investment as an equivalent investment in today’s GOOGL shares and accounting for the 2014 and 2022 splits.

Google’s 2-for-1 split in 2014 and 20-for-1 split in 2022 turned each original IPO share into 40 shares. At $350.50, the $10,000 investment is therefore about $1.65 million.

The surprising takeaway: Google’s IPO was spectacular, but if you had been able to buy Microsoft, Apple, Amazon, or Nvidia at their IPOs, the results would have been dramatically larger.

And there is an even more interesting comparison: if you had put $10,000 into each of all five IPOs—a total of $50,000—you’d have approximately $190 million today. That’s before dividends.

Instead Using the First day of Closing Price

Of course, few investors could have gotten in on the IPO price.

Using the closing price on the first day of public trading, rather than the IPO offering price, gives a more realistic picture of what an investor could have paid if they bought at the end of the first trading day.

I’ve recalculated the figures using the October 7, 2026 closing prices and all subsequent stock splits. The October 7 closing prices were MSFT $529.76, AAPL $336.67, AMZN $259.92, NVDA $237.47, and GOOGL $350.50.

CompanyIPO DateFirst-Day Closing Price$10,000 Invested at First-Day CloseValue Oct. 7, 2026Multiple
Nvidia1999$19.69$10,000$57.90 million5,790×
Microsoft1986$27.25$10,000$55.99 million5,599×
Apple1980$29.00$10,000$26.00 million2,600×
Amazon1997$23.50$10,000$5.31 million531×
Google (Alphabet)2004$100.34$10,000$1.40 million140×

The historical first-day closes are well documented: Apple closed at $29 on its December 12, 1980 debut; Amazon closed at $23.50 on May 15, 1997; Nvidia closed at $19 11/16 ($19.6875) on January 22, 1999; and Google closed at $100.34 on August 19, 2004.  Microsoft’s first-day close is reported as $27.25.

What stands out

Nvidia becomes the winner when you assume you bought at the first-day closing price. A $10,000 investment would be approximately $57.9 million today.

Microsoft is extremely close behind at $56.0 million.

The difference between Nvidia’s $19.69 first-day close and its $12 IPO price was relatively small compared with the enormous appreciation that followed. Microsoft’s first-day close, however, was about 30% higher than its $21 IPO price, making the difference more noticeable.

Amazon is particularly interesting. Buying at the IPO offering price of $18 versus the first-day close of $23.50 makes a huge difference, but even at $23.50, $10,000 would have grown to approximately $5.31 million.

Google is the least spectacular of these five on this particular basis, but $10,000 still became about $1.4 million.

Now if someone would only invent a time machine.

Disclosure: Author may have positions in some of the above at the time the article was written. No investment recommendations are expressed or implied.
Stocks Going Ex Dividend in October 2026

The following is a short list of some of the many stocks going ex-dividend during the next month, which can be helpful for traders and investors interested in the stock trading technique known as “Buying Dividends” or “Dividend Capture.” This strategy involves purchasing stocks before the ex dividend date and selling them shortly after the ex-date at a similar price, while still being eligible to receive the dividend payment.

Although this dividend capture strategy generally proves effective in bull markets and flat or choppy markets, it is advisable to exercise caution and consider avoiding this strategy during bear markets. To qualify for the dividend, it is necessary to buy the stock before the ex-dividend date and refrain from selling it until on or after the ex-date.

However, it is important to note that the actual dividend may not be paid for several weeks, as the payment date may not be until two months after the ex-dividend date.

For investors seeking a comprehensive list of stocks going ex-dividend in the near future, WallStreetNewsNetwork.com has compiled a downloadable list containing numerous dividend-paying companies. Here are a few examples showcasing the stock symbol, ex-dividend date, periodic dividend amount, and annual yield.

Cisco Systems, Inc.(DE) (CSCO)10/2/20260.421.56%
Intuit Inc.(INTU)10/8/20261.382.00%
NetApp, Inc.(NTAP)10/9/20260.520.99%
Phillips Edison & Company, Inc.(PECO)10/15/20260.1153.70%
First United Corporation(FUNC)10/19/20260.282.60%
Prospect Capital Corporation(PSEC)10/28/20260.03520.00%

To access the entire list of numerous ex-dividend stocks, subscribers will receive an email in the next couple days with the full list. If you are not already a subscriber, you can sign up using the provided signup box on this page. Don’t miss out on this valuable information, and the best part is that it’s free!

Dividend Definitions

To better understand the dividend-related terms, let’s define them:

Declaration date: This refers to the day when a company announces its intention to distribute a dividend in the future.
Ex-dividend date: On this day, if you purchase the stock, you would not be eligible to receive the upcoming dividend. It is also the first day on which a shareholder can sell their shares and still receive the dividend.
Record date: This marks the day when you must be recorded on the company’s books as a shareholder to qualify for the dividend. Typically, the ex-dividend date is set two business days prior to the record date.
Payment date: This is the day on which the dividend payment is actually made to the eligible shareholders. It’s important to note that the payment date can be as long as two months after the ex-date.

Before implementing the “Buying Dividends” technique, it is crucial to reconfirm the ex-dividend date with the respective company to ensure accuracy and avoid any unexpected changes.

In conclusion, being aware of the stocks going ex-dividend can be advantageous for traders and investors employing the “Buying Dividends” strategy. WallStreetNewsNetwork.com provides a convenient resource to access a comprehensive list of such stocks, allowing individuals to plan their investment decisions effectively. Remember to stay informed and consider market conditions before employing any investment strategy.

Disclosure: Author may have positions in some of the above at the time the article was written. No investment recommendations are expressed or implied.
The Adaptability Quotient: Rewiring Your Mind for Success in the Next Human Era 

Book Review by Fred Fuld III

The Adaptability Quotient: Rewiring Your Mind for Success in the Next Human Era is one of those books that makes you stop and think—not just about where technology is taking us, but about whether we are personally prepared for the changes ahead.

Alec Litowitz does an excellent job explaining why adaptability may become one of the most important skills for success in the coming years. As artificial intelligence, automation, and other rapidly evolving technologies continue to reshape the workplace and society, simply relying on what worked in the past may no longer be enough. The ability to learn, unlearn, rethink, and adjust could be just as important as traditional intelligence or experience.

What I particularly enjoyed is that this isn’t simply another book about artificial intelligence predicting a futuristic world. It is really a book about people—how we think, how we respond to change, and how we can train ourselves to become more flexible and resilient when the world around us is changing faster than ever.

The concept of an “Adaptability Quotient” provides an interesting way to think about our own ability to deal with uncertainty and change. The book encourages readers to examine their assumptions and develop a mindset that embraces learning rather than resisting change.

I found the book both timely and thought-provoking. Whether you are an employee, business owner, investor, executive, student, or simply someone trying to understand what the next decade may look like, there are valuable ideas here. The message is particularly relevant at a time when AI is beginning to transform so many aspects of our lives.

This is an important book for anyone who wants to do more than simply watch the future unfold. It challenges us to prepare for it—and, perhaps most importantly, to become adaptable enough to thrive in it.

Buy Utilities That Serve Pro-Data Center States: A Great Investment Idea?

by Fred Fuld III

Here is an investment strategy for you: publicly traded regulated electric utilities that have large amounts of committed data-center load in their service territories and are allowed to earn a return on the generation, transmission and distribution infrastructure needed to serve that load.

That distinction is important. A state can be extremely friendly to data centers, but the economic benefit may accrue to a municipal utility, cooperative, independent power producer, or the data-center operator rather than a publicly traded utility.

The timing is particularly interesting. EPRI now estimates that U.S. data centers could consume 9%–17% of U.S. electricity by 2030, versus roughly 4%–5% today. Virginia is already the standout, with data centers consuming more than 20% of the state’s electricity. And just today, the EIA projected U.S. electricity consumption to hit records in both 2026 and 2027, with AI/data centers a major driver. 

My preliminary ranking

StatePlanned DCs*My viewPublicly traded utilities to investigate
Georgia141⭐⭐⭐⭐⭐Southern (SO) / Georgia Power
Indiana54⭐⭐⭐⭐⭐AES (AES), Duke Energy (DUK), NiSource (NI)
North Carolina41⭐⭐⭐⭐⭐Duke Energy (DUK)
Virginia287⭐⭐⭐⭐½Dominion Energy (D)
Ohio57⭐⭐⭐⭐½AEP (AEP), FirstEnergy (FE)
Iowa41⭐⭐⭐⭐Alliant Energy (LNT)
Arizona86⭐⭐⭐⭐Pinnacle West (PNW)
Texas170⭐⭐⭐½AEP, CenterPoint (CNP), Vistra (VST)
Pennsylvania51⭐⭐⭐PPL (PPL), FirstEnergy, Exelon (EXC)
Illinois123⭐⭐⭐Exelon (EXC), Ameren (AEE)

*Pew’s “planned” category includes projects under construction, planned or land-banked. Virginia has 287, Texas 170, Georgia 141, Illinois 123, Arizona 86, Ohio 57, Indiana 54 and Pennsylvania 51. 

But there is a very important development happening right now: the states that were most aggressive in attracting data centers are beginning to push back. So I wouldn’t use “tax incentives” as my primary measure of attractiveness anymore.

1. Georgia may be the most interesting state right now

This one jumps out to me.

Atlanta has actually overtaken Northern Virginia as the largest North American market for data-center construction, with 2,882 MW under construction in the first half of 2026. Northern Virginia remains the largest existing market, but Atlanta’s construction pipeline is remarkable. 

The key utility is:

Southern Company (SO) → Georgia Power

Georgia Power is particularly interesting for your strategy because it has explicitly changed its rules so that large new customers such as data centers pay the costs associated with serving them. It can require longer contracts, minimum bills, financial security and termination payments, while large customers pay local infrastructure costs upfront. 

That’s almost exactly what you want to see as an investor:

data center growth → electricity demand → infrastructure investment → rate base → earnings growth

without as much risk that existing residential customers end up subsidizing the data centers.

SO would be one of my first stocks to investigate.


2. Indiana is extremely interesting

Indiana is less obvious than Virginia or Texas, but I think it could turn out to be one of the better risk-adjusted opportunities.

EPRI specifically identifies Indiana as one of the states where data-center electricity consumption could exceed 20% of total electricity demand by 2030 in its medium scenario. 

And Indiana has done something particularly interesting from an investor perspective.

AES Indiana → AES (AES)

AES has a proposed Google data center in Indiana under a 15-year customer-specific contract. Google would pay 100% of the power costs and 100% of the new infrastructure required for the facility. AES says the arrangement could generate more than $770 million in fixed-cost savings for existing customers over 15 years. 

That’s a very attractive model.

You’re not merely betting that “AI will use lots of electricity.”

You’re betting on:

AI load + regulated utility + long-term contract + customer-funded infrastructure + rate-base investment.

That’s a much better investment thesis.


3. North Carolina — Duke Energy

I’d put Duke Energy (DUK) high on the list.

North Carolina has 41 planned data centers according to the Pew/Data Center Map data, and Duke is directly positioning itself for the load growth.

Duke recently said that data-center growth should produce billions of dollars in customer benefits, with new revenues supporting grid investment and additional energy resources. 

Duke is also developing a framework designed to make sure data centers pay their fair share of the infrastructure costs.

This makes DUK interesting because you get exposure to North Carolina and South Carolina, rather than having to make a single-state bet.


4. Virginia — the biggest opportunity, but also the biggest political risk

This is the obvious one.

Virginia has 287 planned data centers, versus 141 in Georgia and 170 in Texas. It already has the largest data-center concentration in the world. 

The obvious utility is:

Dominion Energy (D)

The economics are spectacular. EPRI projects Virginia’s data centers could represent 39%–57% of the state’s electricity demand by 2030 under its scenarios. 

But there is a catch.

Virginia has become a political battleground over data centers. Dominion’s fuel costs have risen sharply as it has had to purchase more electricity from the PJM wholesale market, and regulators and politicians are increasingly concerned about the effect on residential customers. The Virginia SCC has nevertheless implemented protections that are actually quite favorable from an investment perspective: data centers must sign contracts of at least 14 years, pay at least 85% of transmission/distribution costs regardless of usage, and may have to provide collateral covering up to 60% of minimum charges. 

So I would not eliminate Dominion because of the backlash.

I’d view it as:

Huge data-center opportunity + huge rate-base opportunity + increasing political risk.

That’s a fascinating investment setup.


5. Ohio — particularly interesting because of AEP

Ohio is another one I’d investigate closely.

AEP (AEP) has created a specific Data Center Tariff.

This is particularly revealing: as of February 2026, AEP Ohio had signed binding contracts representing 5,642 MW of data-center load, in addition to 12,219 MW of contracts signed before the tariff took effect. 

That’s an enormous amount of potential load.

And AEP’s tariff is designed so that the data centers bear the infrastructure costs rather than existing customers. 

That’s precisely the sort of information I would want in an investment screen.

The complication is that Ohio has recently begun reconsidering its extremely generous data-center incentives. The state paused new applications, and the broader political backlash is growing. 

But here’s the interesting part:

AEP doesn’t necessarily need Ohio to give data centers huge tax breaks.

AEP needs the data centers to actually connect to its grid and consume electricity.

That’s a different thesis.


6. Iowa — the sleeper

I think Iowa deserves more attention than it gets.

EPRI identifies Iowa as one of the states where data centers could account for an unusually large percentage of electricity consumption. Iowa also has an unusually explicit data-center incentive structure. Qualified data centers can receive sales/use tax benefits on electricity, equipment, cooling systems, power infrastructure, backup generation and batteries, subject to investment requirements. 

The utilities I’d investigate are:

Alliant Energy (LNT)
MidAmerican Energy — privately held subsidiary of Berkshire Hathaway, so not useful for your publicly traded utility strategy.

That makes LNT the obvious stock to investigate.

The downside is that Iowa’s absolute data-center market is considerably smaller than Virginia, Texas or Georgia.


7. Arizona — another interesting growth market

Arizona has 86 planned data centers, according to the Pew data. 

The obvious stock is:

Pinnacle West (PNW) → Arizona Public Service

What’s particularly interesting is that APS is now explicitly saying:

“Growth should pay for growth.”

APS says data centers and other very large customers should pay the infrastructure costs required to serve them, rather than shifting those costs to existing customers. 

That’s exactly the kind of regulatory environment I’d like to see.

The problem is that Arizona is also becoming politically more cautious about data-center development, so I’d put it below Georgia/Indiana/North Carolina.


What about Texas?

Texas is almost a separate category.

It has 170 planned data centers, and Texas is one of the biggest electricity-growth stories in the country. 

Potential stocks include:

AEP
CenterPoint Energy (CNP)
Vistra (VST)

But I would be careful.

Texas is currently experiencing a significant political backlash against data centers. Governor Abbott has moved toward greater restrictions, and new data-center grid connections have faced delays. 

That doesn’t mean Texas data centers aren’t going to happen. Far from it. But it makes Texas a higher-risk, higher-opportunity component of this strategy.

There’s another important distinction: Texas’s ERCOT market is different from the traditional regulated utility model. Consequently, the relationship between data-center electricity demand and a utility’s regulated rate base isn’t as straightforward as it is with Dominion, Southern, Duke or AEP Ohio.


The investment strategy I would actually build

I would not buy utilities simply because they are located in states that are friendly to data centers.

I’d create a five-factor screen:

1. Data-center pipeline

How many MW of data-center projects are actually planned or contracted?

This is more important than simply counting facilities.

A single 1,000-MW AI campus can be more important to a utility than dozens of conventional data centers.

2. Utility ownership

Does a publicly traded utility actually serve the data center?

This eliminates a surprising number of apparent opportunities.

3. Regulatory structure

This may be the most important factor.

You want to see:

Data center → pays utility → utility builds infrastructure → infrastructure enters rate base → utility earns regulated return.

The Indiana/AES and Ohio/AEP models are particularly interesting examples.

4. Contract duration

I’d favor utilities where data centers have signed 10-, 15- or 20-year commitments rather than merely having “announced plans.”

A proposed data center isn’t worth nearly as much as a signed 15-year power contract.

5. Generation and transmission investment

This is where the strategy becomes much more interesting.

A 500-MW data center doesn’t just buy 500 MW of electricity.

The utility may have to build:

  • substations
  • transmission lines
  • natural-gas generation
  • nuclear capacity
  • solar
  • batteries
  • transformers
  • distribution infrastructure

If those investments are included in rate base, the data center can effectively become a catalyst for years of utility capital expenditures.


My preliminary “data-center utility” watch list

If I were constructing a portfolio around this theme today, my first group to research would be:

SO — Southern Company / Georgia Power
DUK — Duke Energy
AEP — American Electric Power
D — Dominion Energy
AES — AES Corporation
PNW — Pinnacle West
LNT — Alliant Energy

I’d put CNP, FE, NI, PPL and EXC in a second group.

And I would treat VST differently because its exposure is more tied to competitive power generation rather than the classic regulated-utility rate-base story.

One particularly interesting conclusion

The idea may actually be better than a simple “buy utilities in data-center states” strategy.

The more sophisticated version is:

Find utilities where hyperscale/AI data centers are forcing large, contracted, customer-funded additions to regulated generation and transmission infrastructure.

That could give you a way to identify utilities before the full earnings impact appears in the financial statements.

Disclosure: Author didn’t own any of the above at the time the article was written. No investment recommendations are expressed or implied.
Four-Letter Words Hidden in SEC Filings

by Fred Fuld III

When I have some free time on my hands and nothing better to do, I sometimes search Securities and Exchange Commission filings for dirty words.

Just kidding!

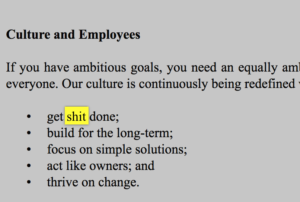
But surprisingly, several companies have actually filed documents with the SEC containing the “S” word and even the “F” word—and these aren’t just obscure companies. Some are names that almost everyone recognizes.

How did these words end up in SEC filings? Sometimes it’s a typo. Sometimes a filing quotes something someone said. And occasionally, the company really does mean what it says.

The “S” Word

One example comes from Shopify (SHOP).

In Exhibit 1.1 to Shopify’s Form 40-F, its 2016 Annual Information Form, the “S” word appears in the Culture & Employees section.

Shopify

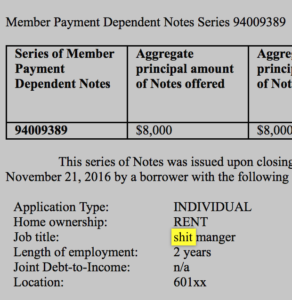
Another example comes from LendingClub.

A Form 424B3 filing appears to contain what may simply be a typo involving an occupation.

LendingClub

The “F” Word

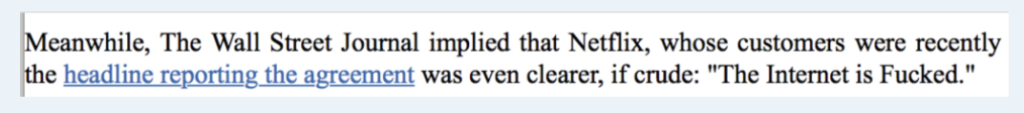
Then there’s Time Warner Cable.

A Form 425 filing contains an interesting quotation that includes the “F” word.

These are just a few examples. There are other SEC filings containing unexpected—and sometimes downright amusing—language, including filings from companies that aren’t nearly as well known as Shopify, LendingClub, or Time Warner Cable.

It just goes to show that you never know what you’re going to find buried in an SEC filing.

And speaking of four-letter words…

Sh1t, I just realized I got through this entire article without using one dirty four-letter word.

Stocks Going Ex Dividend in September 2026

The following is a short list of some of the many stocks going ex-dividend during the next month, which can be helpful for traders and investors interested in the stock trading technique known as “Buying Dividends” or “Dividend Capture.” This strategy involves purchasing stocks before the ex dividend date and selling them shortly after the ex-date at a similar price, while still being eligible to receive the dividend payment.

Although this dividend capture strategy generally proves effective in bull markets and flat or choppy markets, it is advisable to exercise caution and consider avoiding this strategy during bear markets. To qualify for the dividend, it is necessary to buy the stock before the ex-dividend date and refrain from selling it until on or after the ex-date.

However, it is important to note that the actual dividend may not be paid for several weeks, as the payment date may not be until two months after the ex-dividend date.

For investors seeking a comprehensive list of stocks going ex-dividend in the near future, WallStreetNewsNetwork.com has compiled a downloadable list containing numerous dividend-paying companies. Here are a few examples showcasing the stock symbol, ex-dividend date, periodic dividend amount, and annual yield.

Wendy’s Company (The) (WEN)9/1/20260.073.58%
QUALCOMM Incorporated (QCOM)9/3/20260.922.23%
PepsiCo, Inc. (PEP)9/4/20261.484.24%
Steven Madden, Ltd. (SHOO)9/11/20260.211.88%
T. Rowe Price Group, Inc. (TROW)9/15/20261.304.63%
Mondelez International, Inc. Class A (MDLZ)9/30/20260.523.33%
Steel Dynamics, Inc. (STLD)9/30/20260.530.90%

To access the entire list of numerous ex-dividend stocks, subscribers will receive an email in the next couple days with the full list. If you are not already a subscriber, you can sign up using the provided signup box on this page. Don’t miss out on this valuable information, and the best part is that it’s free!

Dividend Definitions

To better understand the dividend-related terms, let’s define them:

Declaration date: This refers to the day when a company announces its intention to distribute a dividend in the future.
Ex-dividend date: On this day, if you purchase the stock, you would not be eligible to receive the upcoming dividend. It is also the first day on which a shareholder can sell their shares and still receive the dividend.
Record date: This marks the day when you must be recorded on the company’s books as a shareholder to qualify for the dividend. Typically, the ex-dividend date is set two business days prior to the record date.
Payment date: This is the day on which the dividend payment is actually made to the eligible shareholders. It’s important to note that the payment date can be as long as two months after the ex-date.

Before implementing the “Buying Dividends” technique, it is crucial to reconfirm the ex-dividend date with the respective company to ensure accuracy and avoid any unexpected changes.

In conclusion, being aware of the stocks going ex-dividend can be advantageous for traders and investors employing the “Buying Dividends” strategy. WallStreetNewsNetwork.com provides a convenient resource to access a comprehensive list of such stocks, allowing individuals to plan their investment decisions effectively. Remember to stay informed and consider market conditions before employing any investment strategy.

Disclosure: Author may have positions in some of the above at the time the article was written. No investment recommendations are expressed or implied.